US Tightens Drone and Robotics Barriers as China Dominates Global Manufacturing
Washington's latest restrictions on foreign-made drones and advanced robotic systems mark a turning point for the global robotics industry, but the tariffs and security measures may not halt China's manufacturing momentum — they'll just redirect it.
In July and August 2026, the United States tightened controls on foreign-made advanced robotic systems and imposed steep tariffs on imported drones and their components, both citing national security concerns. The drone tariffs take effect this month, with additional component tariffs following in 2027. TechCrunch reports the moves are part of a broader effort to restrict foreign technology in strategically important industries.
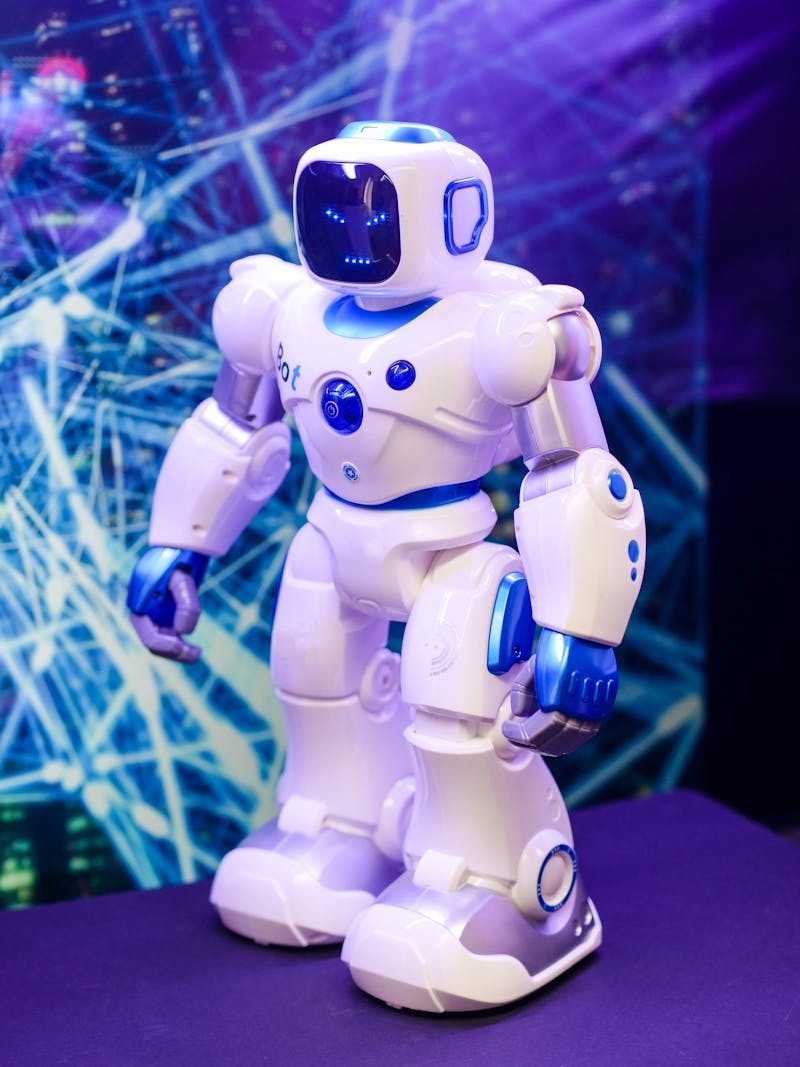
These moves extend the FCC's Covered List, established in 2021, which initially targeted telecommunications and surveillance equipment from Huawei, ZTE, and Hikvision before expanding to foreign-made drones and, most recently, to advanced robotic devices. The list now functions as a de facto procurement ban for federal and federally funded buyers, and its expansion signals that regulators view robots as infrastructure, not consumer gadgets.
The timing reflects China's commanding position in both sectors. Chinese manufacturers dominate global humanoid robot production, with 22,000 units shipped in the first half of 2026 alone — the vast majority from Chinese makers — according to Counterpoint Research. In drones, the picture is similar: Chinese firms control the low-cost consumer and commercial segments, and companies everywhere from farms to film sets fly hardware made in Shenzhen or its satellite manufacturing hubs.
China's Manufacturing Scale Advantage
The world's five largest humanoid robot makers by shipments in the first half of 2026 were all Chinese: AgiBot, Unitree, Galbot, UBTECH, and Leju Robotics. Together, they accounted for 86% of global shipments, according to Counterpoint.
US companies are operating at a far smaller scale, said Soumen Mandal, a principal analyst at Counterpoint Research. That volume gap carries real implications beyond market share.
Lower prices allow Chinese manufacturers to put more robots into use, generating real-world data that can improve their technology. Higher production volumes, in turn, can further reduce costs, said Ankur Saxena, an investment director at TDK Ventures. It's a flywheel that Western startups, with their smaller order books and pricier components, struggle to spin up.
Mandal said Chinese humanoid makers are also pushing costs down by bringing more of the technology stack in-house and drawing on China's existing manufacturing base. Unitree, for example, is developing more components internally, while automakers such as XPeng can draw on their experience in chips and vehicle manufacturing as they move into robotics. Huawei's automotive supply chain, too, sits close enough to robotics that component-level advantages bleed across.
"The United States leads in frontier AI, software, and semiconductor innovation," Saxena told TechCrunch. "China leads in manufacturing scale, supply-chain depth, and cost."
That manufacturing edge has let Chinese companies cut humanoid prices faster than most US competitors can match. Where an early US humanoid might carry a six-figure price tag, Chinese builders have pushed entry-level units toward consumer-electronics territory, often undercutting Western rivals by wide margins on equivalent specs.
"You cannot sanction your way around a cost curve. You can only out-build it, and America has yet to begin making the decade-long investment that will require," Saxena said.
The restrictions may protect parts of the American market, but they don't directly address China's global manufacturing scale and cost advantages. Analysts and executives who spoke with TechCrunch said the result may be less a clean US-China split than a more fragmented global market, with Chinese companies expanding elsewhere while US and allied manufacturers compete in markets where security requirements matter more.
Where Competition Moves Next
Even if Chinese robotics companies lose access to the American market, they still have a large domestic market and room to expand elsewhere, particularly in regions where demand for affordable automation is growing, Saxena said.
Chinese robotics companies are already targeting price-sensitive markets with severe labor shortages across Europe, Southeast Asia, Latin America, and the Middle East, said Mandal.
Mandal expects humanoid makers to follow a path similar to Chinese electric vehicle companies: build scale at home, expand into overseas markets, and eventually establish local production. Countries facing labor shortages and demographic decline could become early markets for humanoids, particularly in manufacturing, where robots can take on repetitive work. The EV playbook — sell cheap at scale, then open assembly plants closer to demand — is nearly identical in outline.
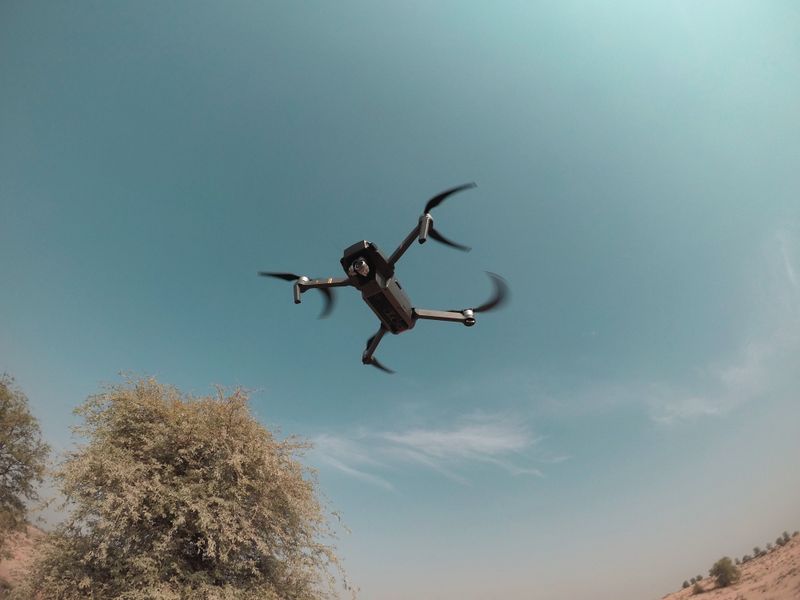
The drone market offers an early glimpse of what that more fragmented robotics market could look like. The industry is increasingly splitting into two ecosystems: a US-led market built around American-made, NDAA-compliant systems, and a China-led market focused on low-cost, high-volume production, said Bentzion Levinson, founder and CEO of Virginia-based drone maker Heven AeroTech.
Levinson said Western manufacturers are unlikely to beat Chinese companies in the low-end consumer drone market, where cost remains a major advantage. Instead, US and allied companies could increasingly compete in long-range autonomous systems for defense and critical infrastructure, where security requirements carry more weight. That's where NDAA compliance — the requirement that equipment used by federal agencies be free of Chinese parts and software — becomes a genuine market-creating rule rather than a paperwork exercise.
Levinson sees the next competitive frontier shifting from the drones themselves to the technology that powers them and the equipment they carry. "The next battleground is over who owns the next-gen energy and payload architecture," he said, pointing to battery constraints in particular. As drones become more capable, battery limitations could make power systems an increasingly important point of competition — a pattern that favors whoever controls cell manufacturing and energy-dense pack design.
Allied Supply Chains as Middle Ground
Agility Robotics welcomed the FCC's decision in July, saying it could address security concerns around foreign-made advanced robots before they become deeply embedded in the US market, as has happened in the drone industry. The company pointed to its Digit humanoid, which is designed and assembled in the US, while also calling for continued access to the tools and technologies needed to advance robotics research.
"The alternative to China isn't a purely domestic US supply chain; it's a diversified allied one," Saxena said.
That could create opportunities elsewhere in Asia. Japan has decades of experience in industrial robotics and precision manufacturing, South Korea brings strengths in electronics, batteries, and automobiles, and Taiwan is a major player in semiconductors. But none can simply replace China, Saxena said, given how deeply Chinese components remain embedded across the global robotics industry — from motors and reducers to sensors and casting.
Asian manufacturers could emerge as a middle ground between lower-cost Chinese robots and more expensive US offerings, Mandal said. South Korea's Hyundai, which owns Boston Dynamics, and Japan's Toyota are among the automakers investing in robotics, drawing on their expertise in vehicles, manufacturing and autonomous systems as they move into humanoid robots.
Yang Fang of Beagle Technology, a California-based agtech startup that uses AI and robotics software to turn conventional farm equipment into autonomous machines, told TechCrunch that robotics is likely to become more regional as companies design machines for the labor needs, working conditions, and customers in their home markets.
Chinese robotics companies, for example, may focus on products suited to China and nearby markets, while US companies are more likely to build for industries across North America, he said.
The result may not be two neatly separated US- and China-led robotics industries. Instead, the restrictions could accelerate the emergence of regional markets: Chinese companies competing on cost and scale across much of the world, US and allied manufacturers gaining ground where security requirements matter most, and manufacturers in Japan, Taiwan, and South Korea trying to carve out space between the two.
For more on the autonomous systems beat, see our Robotics & Drones section, which tracks delivery drones, warehouse automation, and the humanoid race as it unfolds.
Sources: TechCrunch, Counterpoint Research, TDK Ventures